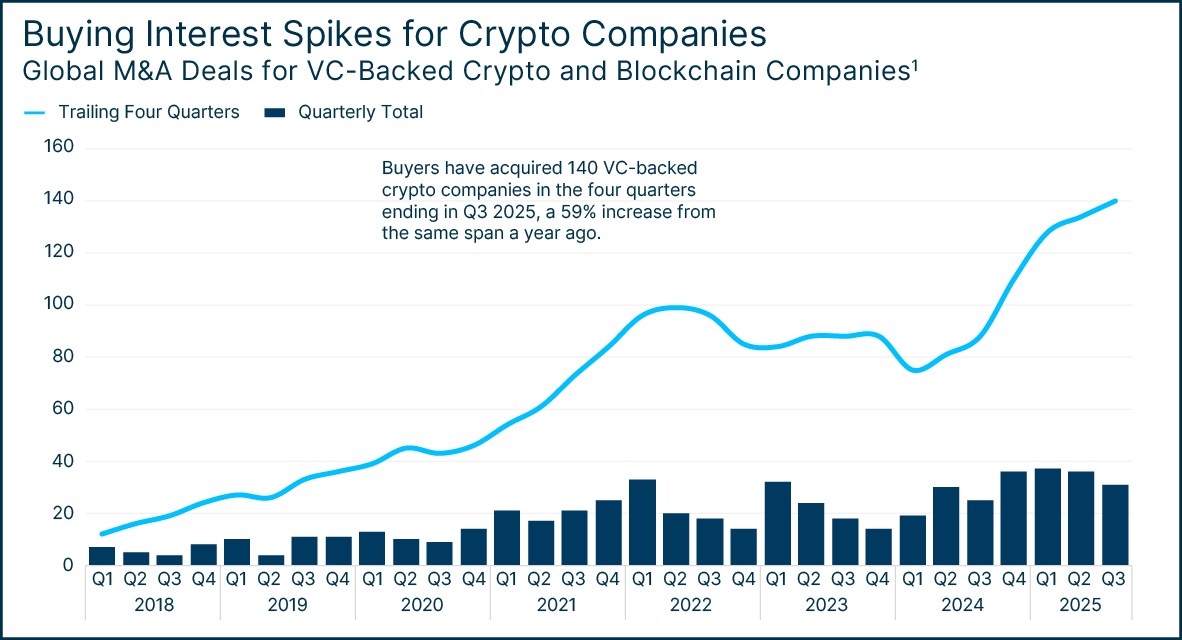
We expect this momentum to continue into 2026. As digital asset capabilities become table stakes for financial services, incumbents are accelerating acquisition strategies rather than building products from scratch. Exchanges, custodians, infrastructure providers and brokerages are consolidating into multi-product companies, a spectrum that stretches from those wanting stablecoin capabilities to full-stack crypto banks that mirror the integrated services of traditional financial institutions.
Full-stack strategies drive consolidation
Ripple is the clearest example of this full-stack strategy, acquiring seven startups in the past two years to expand beyond payments into brokerage, custody and treasury services. Its three largest deals – Hidden Road, a prime brokerage ($1.25 billion), GTreasury, a treasury software provider ($1 billion), and Rail, a stablecoin platform ($200 million) – illustrate the ambition to assemble a vertically integrated global financial platform. These acquisitions helped to vault Ripple’s valuation to $40 billion in November, making it one of the highest-valued unicorns in the US.
In addition, public market activity is reinforcing the IPO cycle. Successful IPOs from Circle, Figure and other blockchain-native companies have reopened the equity window for the sector. These offerings establish valuation benchmarks, return capital to LPs and sharpen investor conviction that mature crypto infrastructure companies can perform like fintech or payments companies in public markets. The result is renewed M&A appetite, both from strategic acquirers seeking to broaden offerings and from VC-backed companies looking to scale through acquisition.
With crypto capabilities increasingly embedded in mainstream finance, 2026 is shaping up to be another year of aggressive consolidation as companies race to build comprehensive, end-to-end platforms. Traditional finance companies are quickly recognizing that they must adapt to crypto or run the risk of being disrupted by it.
3: Stablecoins become the internet’s dollar
Stablecoins are becoming the backbone of digital money. These tokens – typically backed 1:1 by cash and cash equivalents – enable near-instant settlement, programmable compliance and global operability. Compared to ACH or credit card networks, which can take days to clear, stablecoin transactions settle in seconds at materially lower cost.
Corporations are increasingly recognizing the advantages of stablecoins as they modernize treasury and payment operations. Shaving settlement times, and even a few basis points off the cost of each transaction could create significant savings for a company doing billions of dollars in transactions each year. Acknowledging competitive urgency, incumbents don’t want to be left on the sidelines as a new technology disrupts payments.
Regulatory clarity accelerates stablecoin adoption
Regulatory clarity from the GENIUS (Guiding and Establishing National Innovation for U.S. Stablecoins) Act in July 2025 has further accelerated adoption by establishing consistent federal standards.
The US joins regions such as the EU (Markets in Crypto Assets, or ‘MiCA’), UK, Singapore and UAE in explicating frameworks for fiat-backed digital money. With compliance guardrails in place, enterprise integration has picked up pace.
How will stablecoin issuers comply with GENIUS Act mandates in 2026?
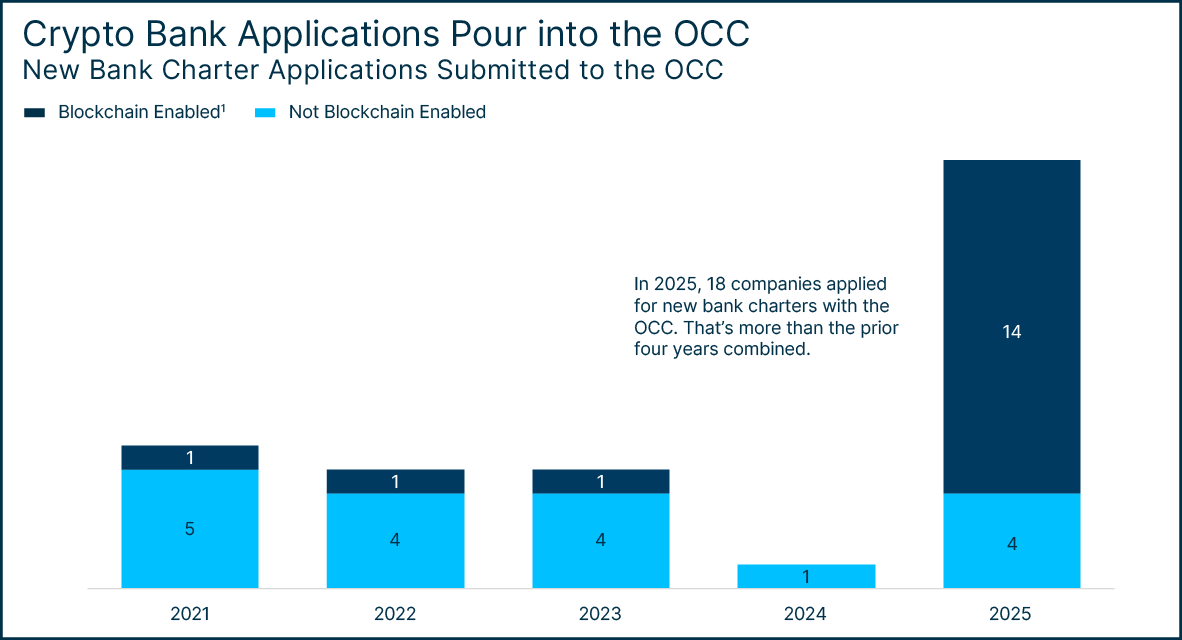
Under the law set to take effect in January 2027, only permitted entities will be allowed to issue stablecoins. For now, this group is limited to licensed depository institutions like banks or credit unions, as well as nonbanks that are approved by the OCC or state regulators. Stablecoins will be required to have a 1:1 backing of reserves in either short-term treasuries or currency, and issuers must comply with KYC/AML rules and disclose the composition of their reserves monthly. Notably, Tether, which issues USDT, the largest stablecoin by market cap, plans to comply with the federal law by issuing a new, compliant stablecoin and then bringing USDT into compliance over time.
Global stablecoin expansion
Global stablecoin supply is now expanding as banks and fintechs issue tokens for remittances, B2B payments and card settlement.
- Société Générale launched its EUR CoinVertible in August.
- JPMorgan extended JPM Coin functionality to public blockchains in November 2025.
- A consortium of US banks – including PNC, Citi and Wells Fargo – is exploring a joint stablecoin initiative through Early Warning Services, the parent company of Zelle.
Stablecoin-as-a-Service
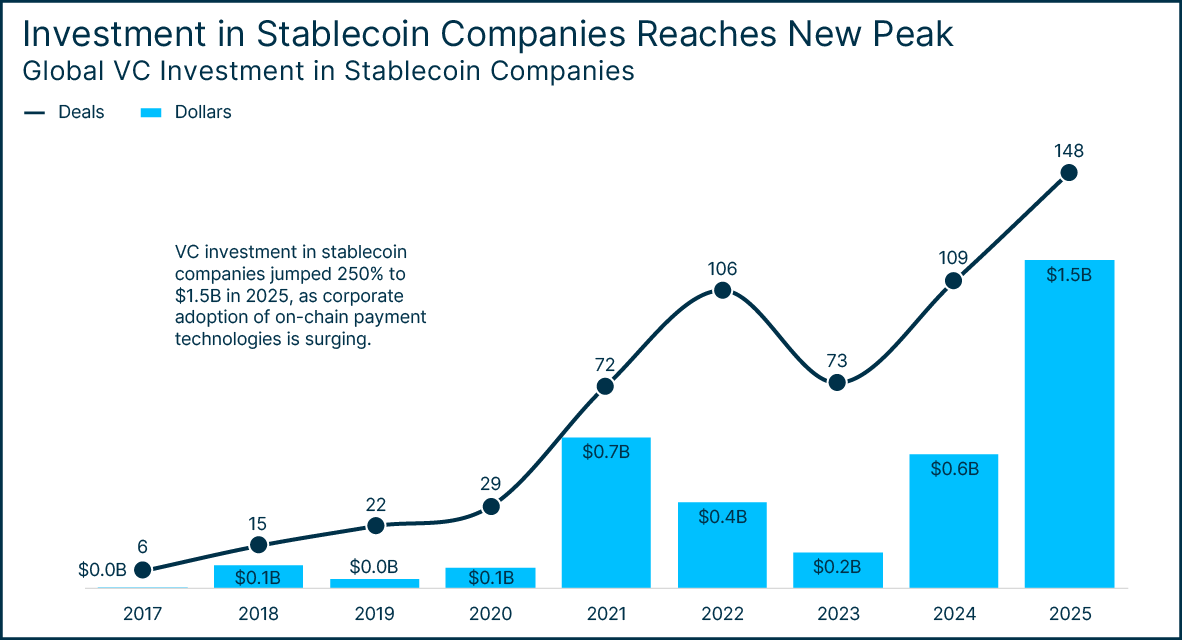
As more institutions turn to on-chain settlement, a new category of infrastructure providers – “Stablecoin-as-a-Service” – has emerged to help corporates launch and manage regulated tokens. Investors have taken note.
- VC investment in stablecoin-related companies totaled less than $50 million in 2019; this year, it exceeded $1.5 billion, flowing to firms such as Tempo and MeshConnect that enable enterprise adoption.
- Paxos, a $2.5 billion VC-backed issuer, mints stablecoins for PayPal, Fiserv and other major payments companies.




 Article