


Jump To
Reports
The Future of Healthtech
Jennifer Friel Goldstein, Dennis He, Nina Kandilian, Alex Lennox-Miller, Anjalika Komatireddy, Raysa Bousleiman
Key takeaways
Healthtech investment is shifting dramatically. Provider operations now capture 44% of healthtech funding, surpassing alternative care as AI-driven solutions transform administrative and clinical workflows. M&A deals dominate exit strategies, while AI valuations climb to 2021 highs.
44%
Of healthtech investment dollars are going to provider operations
If the pace of investment holds, provider ops will have its biggest year ever.
32
Number of M&A deals in provider ops in 2024
The second most active subsector, alternative care, had only 11.
~42%
Boost in seed-stage AI valuations since 2021
AI valuations are growing across the board, but most of all for seed and Series A companies.
Read the full Future of Healthtech report
Get an inside look at the forces driving the sector’s significant growth.
The data
Drawing on over 40 years of expertise, our new healthtech report analyzes the key factors driving healthtech to capture its largest share of healthcare VC investment since mid-2022, particularly in AI-driven provider operations.
INVESTMENT SPENDING
Alternative care loses its crown
Provider operations have taken the lead in healthtech investments, outpacing alternative care and marking a shift from a clinical to an administrative focus.
Provider ops is attracting more VC due to stronger business cases, clear ROI and AI-driven growth.
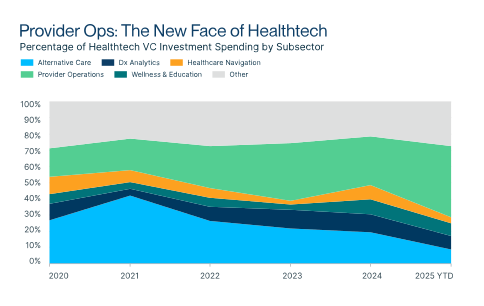 Source: Pitchbook Data, Inc. and SVB proprietary data
EXITS
In provider ops, consolidation drives exit activity
As IPOs have struggled, consolidation through mergers and acquisition has become the dominant exit plan.
Strategic investors and private equity have stepped in to provide liquidity, largely through roll-ups and platform building.
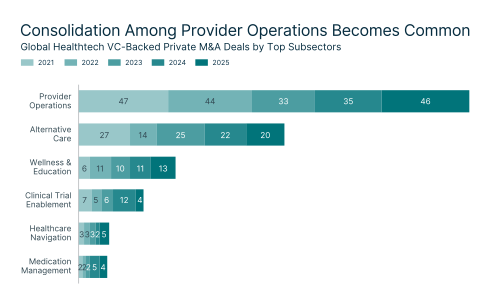 Notes: Exit counts vary from last year’s report due to a switch to a new database. M&A deals are as of 8/31/2025. Source: Pitchbook Data Inc. and SVB proprietary data
VALUATIONS
An AI bubble inflates
Median valuations of AI companies , especially in the early stages, are passing past 2021 highs.
As the AI bubble gets bigger, more experienced healthcare investors are stepping back.
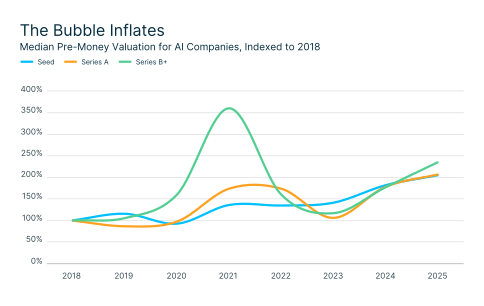 Source: JAMA Health Forum, PitchBook Data Inc., and SVB analysis.
Our insights into the healthtech innovation economy
Learn why healthtech is having its biggest year since at least 2021.
More about the authors
Explore other reports
 Reports
 Report
The Future of Climate Tech
Apr 15, 2026
Jordan Kanis, Eli Oftedal, Josh Pherigo, Andrew Pardo
 Reports
Report
50 BY 2050
Jordan Kanis, Joshua Posamentier, Eliza Cushman, Marianne Wu, Hilla Watkins
 Reports
Report
The State of Corporate Venture Capital 2026
Mark Gallagher, Patrick Eggen, Mikey Kalis, Emma Eschweiler, Abbie Wolf, Anjalika Komatireddy, Eli Oftedal, Jake Ledbetter