Economic vista: The scoop on SOFR
Christi Fletcher, Senior Portfolio Manager
There's a new sheriff in town, and its name is SOFR.
Ever since mid-2023, SOFR became the benchmark interest rate that replaced LIBOR as the standard reference rate for dollar-denominated derivatives and loans, primarily used to price things like adjustable-rate mortgages, corporate loans and financial derivatives. This change may have been technical in nature and largely seamless to consumers, but SOFR is one of those highly technical financial concepts that is worth understanding. After all, it may determine how much it costs you to borrow from a bank, and it can influence how much banks pay on deposits. Plus, it can be an early indicator of banking sector health. So let's break it all down.
Less drama, more transparency
Unlike LIBOR, which was based on bank estimates, SOFR is grounded in actual transactions to the tune of $1T-$2T in daily repo (overnight repurchase) market activity. SOFR is published daily by the Federal Reserve Bank of New York, and it measures the cost of borrowing cash in the repo market using US Treasury securities as collateral. Thus, SOFR is more reliable and harder to manipulate as compared to LIBOR, which suffered a high-profile scandal involving a few global banks. It's worth reiterating that SOFR is secured by US Treasury collateral and thus considered nearly risk-free, and it's a volume-weighted median of all overnight repo transactions.
What, exactly, moves SOFR?
- The biggest driver is Fed policy. When the Fed raises or lowers its fed funds target rate, SOFR typically moves in close alignment because both reflect the cost of short-term dollar funding.
- Since SOFR is based on repo collateralized by Treasuries, the market supply and demand dynamics can move rates. Heavy Treasury issuance can push repo rates (and thus SOFR) higher, while strong demand for Treasuries for collateral can pull it lower.
- Money market liquidity is also an influencer of rates. When cash is abundant in the financial system—for example, after quantitative easing —overnight funding tends to be cheap, and SOFR remains low. During tighter money conditions, often driven by seasonality at quarter- or year-ends when banks pull back lending, SOFR can spike.
- Inflation expectations are also reflected in SOFR trends. Higher inflation typically leads to the Fed tightening policy, which pushes the index higher over time. Falling inflation expectations tend to have the opposite effect.
- During periods of market stress or elevated volatility, risk appetite declines, and we usually see a higher demand for safe-haven liquid assets, like Treasuries. This can create unusual near-term moves in both the repo market and SOFR.
- Finally, the Fed uses tools like the Overnight Reserve Repo Facility and Interest on Reserves Balances to help keep SOFR within a target range. Changes to either of these rates directly affect where SOFR trades.
In short, SOFR is essentially a real-time indicator of short-term dollar funding conditions, heavily influenced by Fed policy but also sensitive to market liquidity, Treasury supply and market stress. In normal times, SOFR and repo yields range just a few basis points below the fed funds rate because supply and demand in the repo market are equal. In those atypical times when SOFR is above the fed funds rate, market participants tend to take notice.
SOFR > fed funds rate
Today, SOFR remains slightly elevated primarily due to tight liquidity in the overnight repo market, which is driven by heavy Treasury issuance, the Fed's ongoing balance sheet reduction (also known as quantitative tightening) and high demand for cash to fund dealer inventories. When cash is scarce relative to Treasury collateral, repo rates rise and push SOFR up. Other market drivers can be Treasury debt settlements and corporate tax payments. If they coincide, we expect to see large amounts of cash being pulled from the financial system and deposited into the Treasury's account at the Fed, which will then reduce the overall supply of reserves available to lend. The combined effect of these flows means that banks and primary dealers will need an immediate influx of cash to meet their settlement and payment obligations. This will elevate their demand for secured overnight funding, thus pressuring SOFR higher.
This situation clearly shows the impact of tight money market conditions on the secured funding rate, confirming that structural events and periodic cash drains are indeed potent drivers of SOFR volatility. However, we do not think this represents severe tightening of liquidity or mounting pressure in US funding markets. Rather, this dynamic is likely temporary, and we think it demonstrates a healthy ability for the market to self-correct.
Credit vista: Banking regulatory radar
Edward Lee, CFA, Senior Credit Analyst
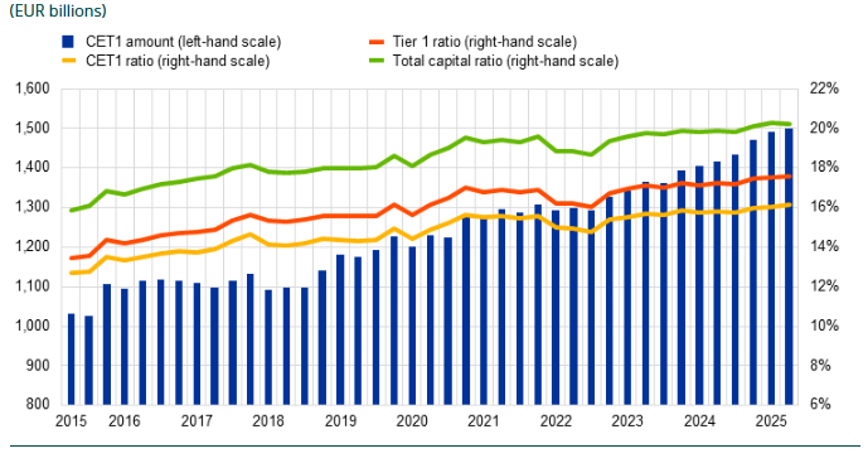
Nearly three years have passed since the banking turmoil of 2023, which saw the collapses of several large regional banks in the US, as well as the failure of Credit Suisse in Switzerland. To an extent, those events exposed gaps in banking regulatory reforms that have been made since the Global Financial Crisis (GFC), from shortcomings in liquidity risk requirements to the absence of effective US regulations for interest rate risk in the banking book (IRRBB – a measure of risk to a bank's capital and earnings that could arise from an array of interest rate shock scenarios). The turmoil in 2023 also highlighted other emerging risks, such as the velocity of deposit flight in an era of increasing digitalization.
Perhaps more so, the events served as a reminder that depositor trust and confidence form the bedrock on which every bank must stand, sometimes irrespective of static fundamentals and capital ratios. And while fundamentals are often front and center, the regulatory frameworks in which banks operate also play a central role, not only as a backstop to excessive risk taking, but also as a champion for depositor trust. It is no surprise, then, that rating agencies put significant weight on the strength and effectiveness of regulatory frameworks for their bank rating methodologies. As S&P notes, "strong prudential regulation and effective supervision is fundamental to banks' credit strength."D We agree with this and thus wanted to dig into the regulatory environment to see what might be on the horizon and the possible implications for debt investors.
Regulations matter
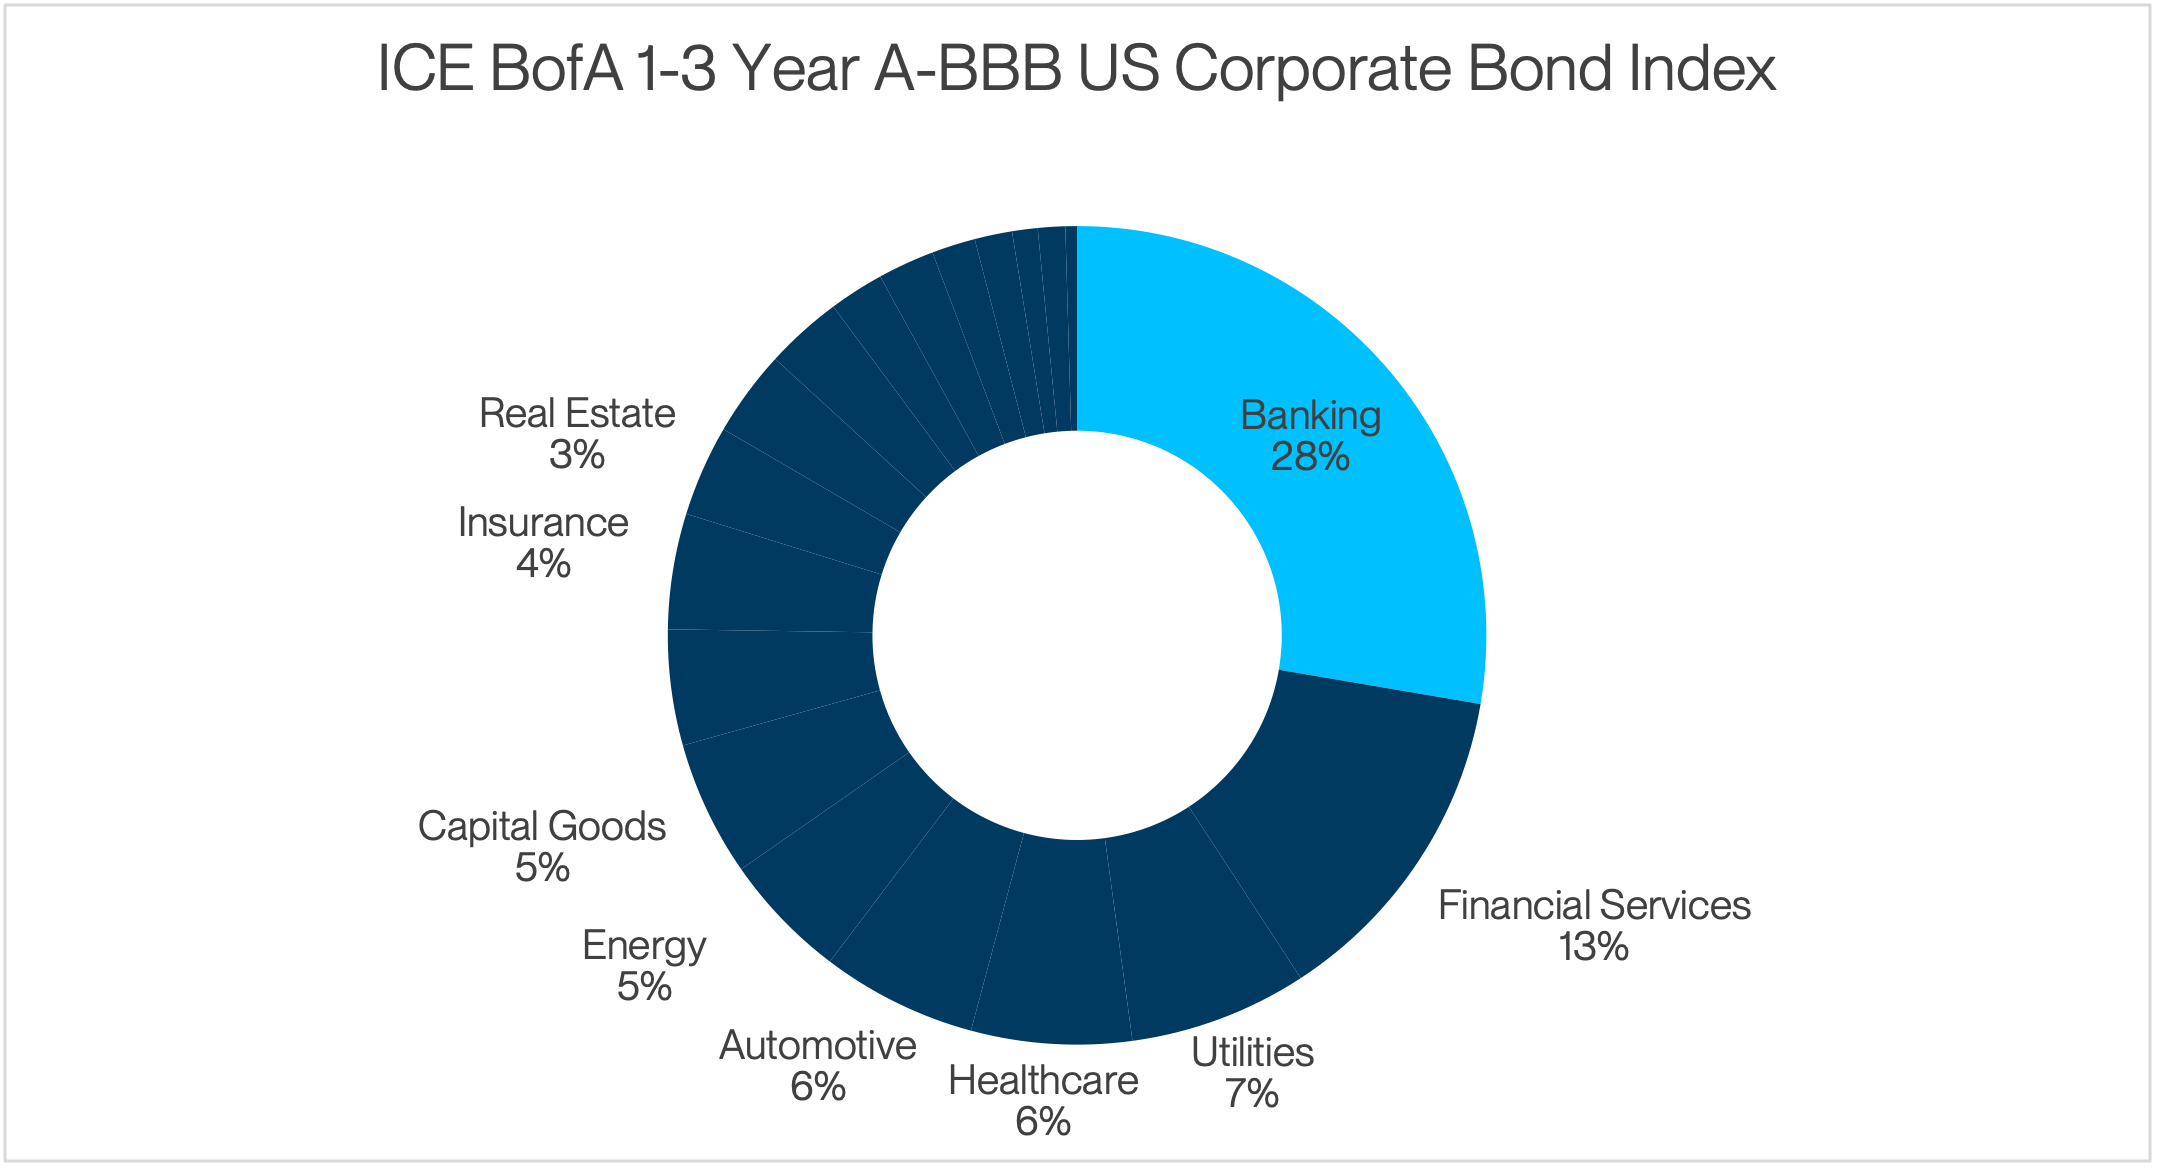
Regulations matter for banks, and banks matter to the overall credit market environment. After all, banks constitute the largest sector weight of US dollar-denominated, broad-sector investment grade corporate bond indexes. Within the Bloomberg US Corporate Bond Index (ticker: LUACTRUU), the standard benchmark for the investment grade corporate bond market, debt securities issued by banks account for ~22% of the total index outstanding. The concentration is even higher for indexes focused on the front end of the corporate credit curve, with banks accounting for 28% of the ICE BofA 1-3 Year A-BBB US Corporate Index. At first glance, this may not seem like an overly large share, but when one considers that the next largest non-financial sector weight is utilities at 7%, the strong relative sway of banks is clear. Large banks dominate the front end with their high regular issuance cadence, driven by regulatory requirements (i.e., total loss-absorbing capacity [TLAC], high-quality liquid assets [HQLA]), as well as the need to fund lending activities at a spread. Yankee banks, particularly those with significant holdings of US dollar-denominated assets and without any meaningful US retail deposit base, account for nearly half the issuance by all banks.

 Article