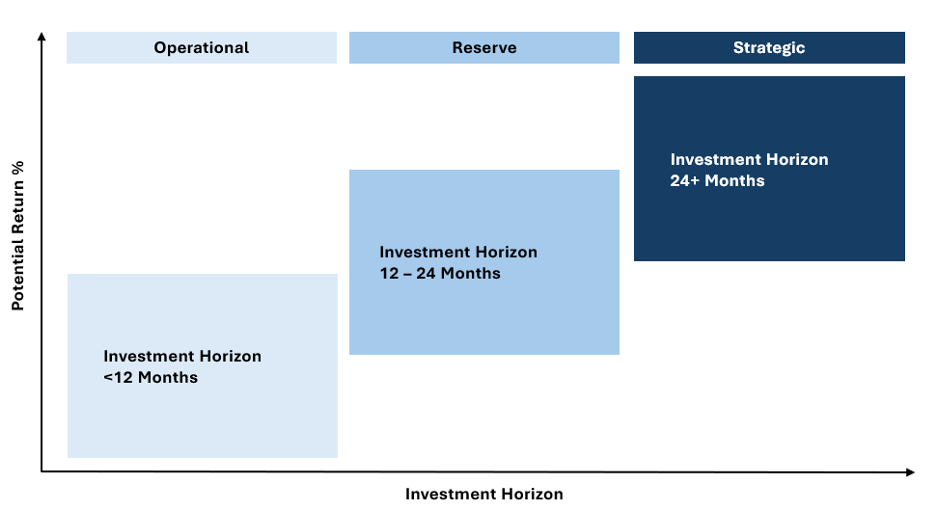
Ultimately, we believe that effective cash management starts with recognizing that not all cash serves the same purpose. Segmenting liquidity into distinct cash buckets allows each portion of the portfolio to be managed according to its specific function, while maintaining capital preservation as its core principle across all segments. For example, treasurers may want to consider a three-bucket approach along these lines:
- Operational cash (<12 months): Operational cash supports daily obligations, including payroll, vendor payments and near-term debt service. Immediate liquidity is the primary focus.
- Reserve cash (12-24 months): Reserve liquidity provides a buffer for unexpected working‑capital needs. In the current environment, modestly extending maturities within this segment can enhance yield while preserving flexibility and prudent risk controls.
- Strategic cash (>24 months): Strategic cash represents capital unlikely to be needed in the near term. This segment can tolerate additional duration in pursuit of improved risk-adjusted returns.
The Fed pause isn't permanent
A Fed pause in April does not imply a static environment, and parking all your cash in money market funds is not a viable set-it-and-forget-it strategy. Possible shifts in energy markets, labor data and geopolitics, as well as changes in Fed leadership, could quickly alter the outlook. The current higher-for-longer window presents an opportunity to reassess your portfolio structure, manage reinvestment risk and ensure investment policies allow sufficient flexibility to adapt. The pause offers time but not permanence. In cash management, standing still is always an option, but it's rarely the optimal response to ever-changing market and economic conditions.
Credit vista: A shifting foundation
Emelynn Abreu, Credit Analyst
A solid foundation for any home is critical to ensure its structural integrity, stability and longevity. One might also say that the bond market provides a similar foundation for the entire housing market. Over the past two decades, we’ve seen both significant and nuanced changes in this foundation, and we continue to monitor the shifts. From our viewpoint, however, the housing bond market still looks to play an important role for income portfolios, even as the market continues to evolve.
A look back
In 2008, during the global financial crisis, the US government placed Fannie Mae and Freddie Mac into conservatorship under the oversight of the Federal Housing Finance Agency (FHFA), after mounting mortgage losses threatened the companies’ solvency and the stability of the housing market. FHFA assumed control of the companies to stabilize operations, preserve their assets and ensure continued support for the US mortgage market. As part of the rescue, the US Treasury entered into Senior Preferred Stock Purchase Agreements with both companies and injected roughly $191 billion of capital into both Fannie Mae and Freddie Mac.D
As a result, since the government’s takeover during the 2008 Great Financial Crisis, Fannie Mae and Freddie Mac debt has been viewed nearly as creditworthy as US Treasury securities, thanks to implicit government guarantees. Credit rating agencies, such as Moody’s and S&P, tie the credit ratings of Fannie and Freddie to that of the US government, given the critical role that Fannie Mae and Freddie Mac’s mortgage-backed securities (MBS) play in the US housing market. Together, Fannie Mae and Freddie Mac own or guarantee more than $7 trillion of mortgage debt or roughly 70% of the US housing market, underscoring its pivotal influence in housing finance, residential and multifamily property values and the broader US economy.D
A look at spreads
Consider the spread between US agency bonds, such as Fannie Mae and Freddie Mac, and US Treasuries. Treasuries are explicitly guaranteed by the full faith and credit of the US government, while Fannie and Freddie debt is supported by an implicit government guarantee. Although investors broadly expect government support in times of stress, as demonstrated during the 2007-2008 financial crisis, investors still demand a credit premium in lieu of the explicit legal guarantee. This component of the spread tends to widen when there is heightened concern about housing policy, political risk or the future status of the government-sponsored enterprises.
Since the start of the second Trump administration, policy makers have expressed a desire to privatize the government-sponsored enterprises (GSE) via an initial public offering. This is not a simple undertaking, and the process involves navigating various complex and untested legal issues. Chief among these is the significant question regarding the existing Senior Preferred Stock held by the Treasury, which is roughly a $323 billion shortfall under current risk-based capital requirements.D Who might be responsible for this shortfall, and what would be the role of the government following privatization (if any role at all)? Another central question is the fate of that implicit government guarantee. Will it still exist? How might that affect Agency MBS spreads? And ultimately, where would Agency MBS fit in portfolios going forward?
If Agency MBS are no longer considered to be quasi-government securities, investors might demand wider spreads and see liquidity dry up to some degree. Prior to the 2008 Great Financial Crisis and before Fannie Mae and Freddie Mac were placed in conservatorship, spreads between US Treasuries and the Agencies widened considerably, by as much as 150 bps at the peak, only to tighten to levels near those of US Treasuries when the federal government took over the companies.
Under privatization, if the government guarantee becomes weaker or disappears altogether, investors would undoubtedly demand more credit compensation and thus wider spreads. In turn, Fannie Mae and Freddie Mac indebtedness would become true corporate credit risk, and pricing might mimic high-grade financials. A survey of MBS investors expects that privatization under the GSE’s current and severely undercapitalized levels could lead to a widening of risk premiums by as much as 45 bps or more.D However, some analysts estimate that in a scenario where the GSEs retain government support and are better capitalized, spreads might widen by a much more modest 10-20 bps versus Treasuries.
Equally as important as the fate of the implicit government guarantee, some argue that spreads would ultimately depend on a broader set of structural considerations in any Fannie Mae and Freddie Mac privatization scenario. These include: the amount of capital held by the GSEs; the preservation of more recently created Uniform Mortgage-Backed Securities (UMBS) and TBA market liquidity; and whether banks, regulators and the Fed continue to treat agency MBS as quasi-sovereign risk assets. These answers could be just as important as the guarantee itself.
We will be closely monitoring how the proposed privatization measures and other changes to the housing bond market affect their risk profile and spreads. Ultimately, that will determine their role in any broader fixed income portfolio.
Markets




 Article