Value proposition | Help stabilize your projected NAV (net asset value) or cost and mitigate the impact of currency fluctuations while earning additional FX carry trade returns.
FX Risk Advisory for Private Fund CFOs
Exit hedging: NAV-based FX hedging
Ivan Asensio, Ph.D.
Jump to
Situation
US-based private-equity fund holds euro-denominated assets with an anticipated holding period of 5 years. The projected internal rate of return (IRR) for the project, measured in US dollars (USD), is 20 percent per annum. No cash flows are anticipated prior to exit.
Equity capital(USD) $100.00
Projected IRR 20%
EURUSD spot 1.20
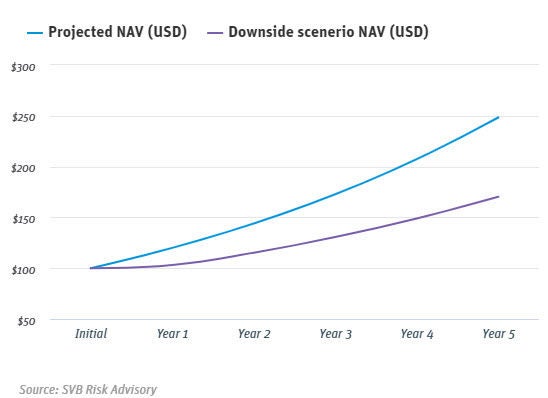
* There is a 10 percent probability the euro can depreciate by this amount over a 5-year period, according to FX option markets.
Risk quantification
A depreciation in the euro will adversely impact realized IRR. For instance, we can assign a 1 in 10 chance that the euro may depreciate over the 5-year investment period such that IRR will deteriorate from the projected 20 percent to 11 percent when the final cash flow is repatriated back to USDD.
Solution
An FX forward is a contractual obligation to exchange one currency for another at a predetermined fixed rate and a specific date in the future. When used in risk management situations, FX forwards offer downside protection, IRR certainty and in certain situations, favorable pricing over prevailing spot rates.
Trade details
EUR/USD spot reference: 1.2000
Direction: Sell EUR / Buy USD
Notional: €207.36mio
Contract rate: 1.3800
Tenor: 5-year
Notes: Contract rate for selling EUR is more favorable than the prevailing spot rate. Notional is generally set at the initial equity injection amount, or at some percentage of the projected NAV at expiry.
Carry trade boost
The pricing of FX forward contracts is derived from three market factors: 1) spot exchange rates, 2) interbank interest rate differentials and 3) cross-currency basis swap rates.D For EUR/USD forwards, because US interest rates are higher than EU interest rates (net of cross-currency basis), the hedger receives a better rate for selling euro in the forward market as opposed to the spot market. This carry trade boost for euro sellers improves with the trade tenor and, at over 3 percent per annum in early 2018, is at its highest point since the euro was launched in 1999. This phenomenon is primarily the result of divergent monetary policies between the Federal Reserve and the European Central Bank.
Hedged outcomes
Fund hedges 100 percent of projected NAV with an FX forward and locks in 23 percent IRR (assuming no date or notional mismatches between exposure cash flows and hedge).
Equity capital(USD) $100.00
Projected IRR 20%
EURUSD spot 1.20
FX forward hedge $100.00
* There is a 10 percent probability the euro can depreciate by this amount over a 5-year period according to FX option markets.
Additional considerations
- Realized NAV may differ from initial projected NAV, potentially resulting in mismatches between exposure and hedge amounts. This may be addressed by keeping hedge ratios under 100%.
- A window may be incorporated into the forward to accommodate expiry date flexibility, helping avoid a cash event on the deal back-end. A cash event describes a situation where there is a mismatch between the expiry of the derivative and the timing of the underlying cash flow. This is undesirable, as it may result in a cash outlay needed to settle the forward which is not offset by the cash inflow from the real business venture.
- For unanticipated early exits, forwards may be unwound early. The investor would be exposed to movements in forward curves (i.e., from forward point claw-back).
- Forward hedges do not offer upside participation from euro strength. Deferred premium put options or put option spreads may be used if asymmetry is desired.
- FX credit lines are required to execute long dated forwards.
If you'd like to discuss your specific risk profile, contact Bobby Donnelly at bobby.donnelly@firstcitizens.com, West Coast/Central, or Ben Johnston at ben.johnston@firstcitizens.com, East Coast. You can also contact the author, Ivan Oscar Asensio, Head of FX Risk Advisory, at ivan.asensio@firstcitizens.com.
Read our other FX Risk Advisory.
Read next
Explore these related articles to help you stay on top of the latest data, insights and developments in the venture-backed crypto and blockchain ecosystem.
 US Treasuries
 Article
Treasury market infrastructure: How it shapes corporate cash investing
Oct 28, 2026
Jose Sevilla, Jason Graveley
 Global Trade Finance
Article
Using a Standby Letter of Credit for a commercial lease to support real estate expansion
Oct 26, 2026
Justine Nguyen, Dennis Brown
 Spend Management
Article
Startup expense management: Moving from manual processes to scalable controls
Oct 23, 2026
Angela Sellers