


Jump To
Reports
State of the Markets
H1 2024 | Our Innovation Economy Outlook
Marc C. Cadieux, Mark Gallagher, Eli Oftedal, Josh Pherigo, Andrew Pardo
Key takeaways
Our H1 2024 State of the Markets report finds that, two years into the most significant contraction of the innovation economy since the dot-com crash, signs of normalization – and even recovery – are emerging.
1 in 4
Funds closed in 2023 focused on AI
Innovation related to artificial intelligence was a bright spot, driving a large portion of US VC fundraising and investment in 2023.
67%
Of US VC-backed tech companies reduced net burn
Tech companies are adapting to the new financial normal, with the highest number in recent history reporting year-over-year reductions in net burn rates.
+60%
Of companies went on to raise another equity round following a down round
Down rounds aren't the end of the line, which is a good sign when at least 13% of all US VC deals in 2023 were down rounds.
Explore the full State of the Markets report
Gain perspective into the emerging trends shaping the innovation economy.
The data
In this biannual report, we dive into the current state of the market and key trends, leveraging our proprietary data to offer a unique perspective on recent macroeconomic, fundraising and investment developments.
INVESTMENTS
Investors get more selective
A rising number of patents held by funded companies suggests investors are seeking technical differentiation to guide their funding decisions.
As capital has become more constrained, investors have sought out companies with greater intellectual property than their peers. Companies with more than 15 patents showed greater resilience in deal activity, with a decline 14% less severe than companies with fewer patents.
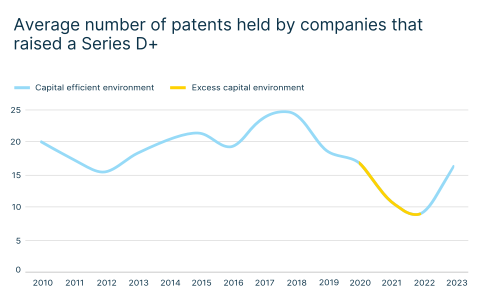 Note: The average number of patents, while a telling measure for trends afoot in the overall economy, is heavily influenced by the top quartile of companies which have significantly more patents than those in the bottom quartile. Data prepared by PitchBook Data, Inc., while the sample size is statistically significant, a large percentage of US VC-backed companies to not have patent information. Source: PitchBook Data, Inc., PitchBook Data, Inc. custom analysis and SVB analysis
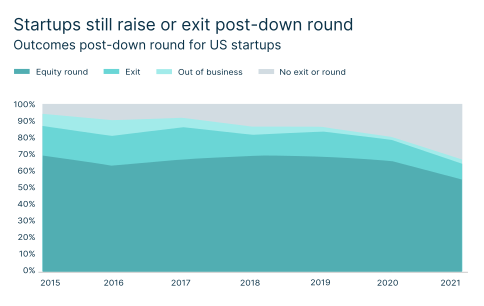 Note: Analysis looks at only the next deal (either exit via buyout or M&A or equity raise) immediately following the down round. If a startup has not raised an equity round or exited via buyout or M&A it is classified as “No exit or round.” Source: PitchBook Data, Inc. and SVB analysis
STARTUPS
Down rounds aren't the end of the line
A down round isn't all bad. In fact, roughly 70% of companies go on to raise another equity round after taking a down round.
Dating back to 2015, for companies that raised another equity round the median valuation increase following a down round is north of 100%.
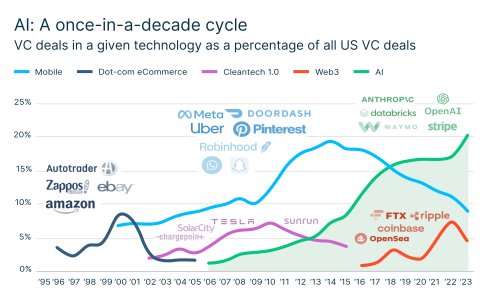 Source: PitchBook Data Inc., Preqin and SVB analysis
TECHNOLOGIES
AI takes center stage
AI technology was the focus of one in four funds that closed in 2023, joining an investment cycle that has steadily increased for the past decade.
ChatGPT has ushered in a new era for AI that could unlock the potential of a long-term investment cycle in the same way that the iPhone did for mobile technology.
RUNWAY
Cash-heavy companies are running out of runway
Roughly half of US VC-backed startups will be out of cash by Q4 if they do not raise – the highest share since 2019.
Companies with the most cash runway have seen the largest declines in runway, reducing the spread between those in the top decile and those in the bottom decile by 40% since 2021.
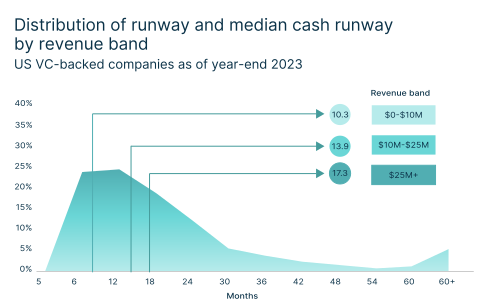 Note: Tech sectors determined using SVB proprietary taxonomy. Runway data is as of 12/31/2023. Source: SVB proprietary data and analysis
More about the authors
Explore other First Citizens Innovation Banking Reports
 Reports
 Report
The Future of Healthtech 2026
Nov 09, 2026
Megan Scheffel, Adam Tweedy, Dennis He, Matt Donne, Alex Lennox-Miller, Urbashee Paul, Josh Pherigo
 Reports
Report
The Future of Fintech 2026
Oct 13, 2026
Nick Christian, Brian Foley, Julie Wagne, Sophie McNaught, Josh Pherigo, Eli Oftedal, Andrew Pardo
 Reports
Report
The Future of Climate Tech
Apr 15, 2026
Jordan Kanis, Eli Oftedal, Josh Pherigo, Andrew Pardo